Full explanation
Overview
Your company just signed a four-year equipment lease: fifty thousand euros a year, paid at the end of each year. Here's exactly how that becomes a lease liability — and the journal entry that goes with it.
A four-year lease, €50,000 a year
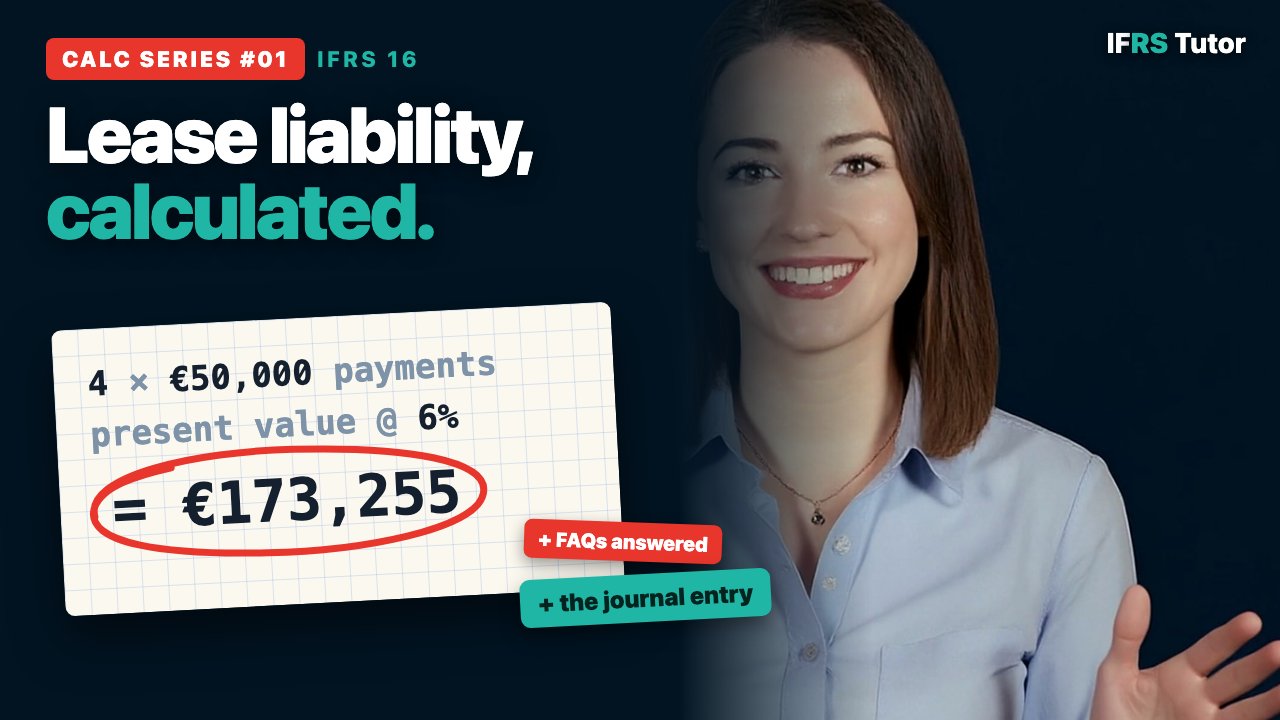
Four-year lease. Fifty thousand euros every year, paid in arrears. No purchase option, no residual value guarantee. And the rate implicit in the lease isn't stated — so it can't be readily determined.
Lease liability = present value of unpaid payments
IFRS 16 is clear on what happens next. At the start of the lease, measure the lease liability at the present value of the payments you haven't paid yet — discounted at the rate implicit in the lease if you can work it out, or your incremental borrowing rate if you can't.
Where the incremental borrowing rate comes from
So where does that rate actually come from? Not a guess, and not just your company's existing loan rate. The standard build-up approach, documented in the Big Four accounting firms' own lease discount-rate guidance, starts with a risk-free reference rate — a government bond yield for a similar term. Add your company's own credit-risk spread. Then adjust for the security the leased asset provides.
Discount each €50,000 payment back to today
For this example, say that build-up lands at six percent. Discount each fifty-thousand-euro payment back to today. The first payment is worth forty-seven thousand, one hundred seventy euros right now. The second: forty-four thousand, five hundred. The third: forty-one thousand, nine hundred eighty-one. And the fourth has fallen to thirty-nine thousand, six hundred five. Add all four together, and the lease liability is one hundred seventy-three thousand, two hundred fifty-five euros.
Dr Right-of-use asset · Cr Lease liability
That number goes straight into two accounts. Debit right-of-use asset, one hundred seventy-three thousand, two hundred fifty-five euros. Credit lease liability, the same amount — assuming no initial direct costs and nothing paid up front. Then, every year, three entries follow. Interest unwinds on the liability: ten thousand, three hundred ninety-five euros in year one. The fifty-thousand-euro payment reduces the liability. And the right-of-use asset depreciates straight-line over the shorter of the lease term and its useful life — here, four years: forty-three thousand, three hundred fourteen euros a year.
Using the wrong rate entirely
The most common slip: using the company's general corporate borrowing rate instead of building a rate specific to this lease — its term, its security, the asset itself. Get the rate wrong, and both the lease liability and the right-of-use asset are wrong from day one.
Do variable payments go into the lease liability?
Do variable lease payments go into the lease liability? Not automatically. Only payments that are fixed — or fixed in substance — are included. A payment the contract calls variable but which you cannot actually avoid in practice is treated as fixed. But true variable payments — those that genuinely depend on usage, volume, or performance — stay out. They hit profit or loss only when you incur them. So a payment that varies with the volume of goods moved through a warehouse: excluded. A payment described as variable but always the same amount in practice: included. The test is not the label on the contract — it is whether the payment is truly avoidable.
What triggers a lease liability remeasurement?
What triggers a remeasurement of the lease liability? Three events. First: you change your assessment of whether you will exercise an extension option or a purchase option. If you assumed you would not extend, but it now looks likely that you will, you increase the lease liability to reflect the additional payments. Second: a modification — a change to the original contract — that is not treated as a separate lease. Third: variable payments linked to an index or rate are remeasured when they actually change. In all three cases, the adjustment goes to the right-of-use asset, not to profit or loss. The liability and the asset move together.