Full explanation
Cost model vs revaluation model
IAS 16 paragraph 29 gives two measurement options after initial recognition: the cost model (carry the asset at cost less accumulated depreciation and impairment) and the revaluation model (carry at fair value at the date of revaluation, less subsequent accumulated depreciation and impairment). Once chosen, the model applies to the entire class of assets — land and buildings is one class, plant and machinery is another. You cannot use the revaluation model for a single convenient property while keeping the rest on cost.
The revaluation model is more common for property — where fair values are accessible via independent valuations — and less common for general plant and machinery, where market evidence is harder to find. The standard is clear: revaluations must be carried out with sufficient regularity to ensure the carrying amount does not differ materially from fair value at the reporting date.
The scenario: a €500,000 building revalued after ten years
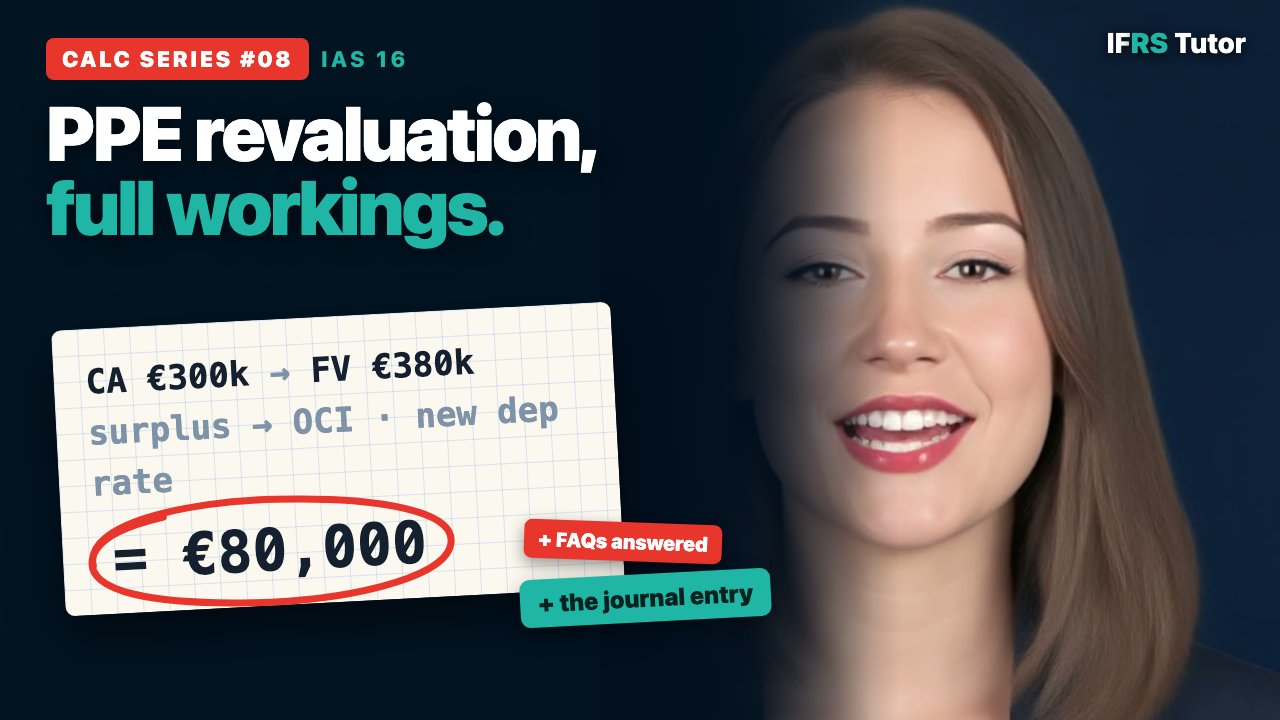
Original cost: €500,000. Total useful life: 25 years. Depreciation method: straight-line. After 10 years: accumulated depreciation of €200,000 (10 × €20,000). Carrying amount: €300,000. A professional valuation at year 10 gives a fair value of €380,000. The required write-up is €80,000 — the difference between the fair value of €380,000 and the carrying amount of €300,000.
Two methods for recording the revaluation: proportional vs elimination
IAS 16 paragraph 35 permits two methods. The proportional method restates both the gross cost and the accumulated depreciation in the same ratio, so that the net carrying amount equals fair value. If the carrying amount of €300,000 is being restated to €380,000, the factor is 380/300 = 1.2667. Gross cost becomes €500,000 × 1.2667 = €633,333. Accumulated depreciation becomes €200,000 × 1.2667 = €253,333. Net: €380,000. The gross figures increase but the net result is the same.
The elimination method is simpler and more widely used in practice. Step one: eliminate all accumulated depreciation against the gross cost — the net carrying amount is now the same as the gross cost (€300,000). Step two: write up the gross cost to fair value — debit PPE €80,000, credit revaluation surplus in OCI €80,000. The asset now sits at gross cost = €380,000, accumulated depreciation = zero.
The elimination method journal entries
Step one — eliminate accumulated depreciation: debit accumulated depreciation €200,000, credit PPE at cost €200,000. After this entry the gross cost is €300,000 and accumulated depreciation is zero — the carrying amount is still €300,000.
Step two — write up to fair value: debit PPE at cost €80,000, credit revaluation surplus (OCI/equity) €80,000. After this the gross cost is €380,000, accumulated depreciation remains zero, carrying amount is €380,000.
The revaluation surplus of €80,000 goes into OCI for the current period and then accumulates in the revaluation reserve in equity. It does not pass through profit or loss.
New depreciation after revaluation
After the revaluation, the building has a carrying amount of €380,000 and a remaining useful life of 15 years (25 − 10). New annual straight-line depreciation: €380,000 ÷ 15 = €25,333. Journal entry each year: debit depreciation expense €25,333, credit accumulated depreciation €25,333.
Note that €25,333 is higher than the pre-revaluation charge of €20,000 per year. The revalued amount is higher, so the depreciation charge increases. This flows through P&L each year — only the initial write-up avoids P&L (it goes to OCI). The ongoing higher depreciation charge is a real cost to the income statement.
The piecemeal transfer of the revaluation surplus
IAS 16 paragraph 41 permits an optional annual transfer from the revaluation reserve to retained earnings. The transfer equals the difference between depreciation based on the revalued amount and depreciation that would have been charged on the historical cost: €25,333 − €20,000 = €5,333 per year. This is a transfer within equity (debit revaluation reserve, credit retained earnings) — it never passes through profit or loss. By the time the asset is fully depreciated or disposed of, the entire revaluation surplus of €80,000 has been transferred to retained earnings: either gradually over the 15 remaining years (€5,333 × 15 = €80,000) or in a lump sum on disposal.
Common mistake 1: continuing the old depreciation rate after revaluation
The error that appears most consistently in practice: a company revalues the building but forgets to recalculate depreciation. The old charge of €20,000 per year continues. This understates depreciation expense by €5,333 per year and overstates both profit and the asset's carrying amount. The carrying amount will diverge from fair value more rapidly, requiring more frequent revaluations to avoid a material difference — and likely a larger write-up at the next revaluation date. Always recalculate depreciation immediately after a revaluation using the new carrying amount and the remaining useful life.
Common mistake 2: treating the revaluation surplus as distributable
The revaluation reserve of €80,000 sits in equity, but it is not a distributable reserve in most jurisdictions. Distributing it as a dividend would be distributing unrealised gains. Under IAS 16, the surplus can only flow to retained earnings through the piecemeal depreciation transfer or upon disposal. Some entities mistakenly treat the full balance as distributable profit. This is both an accounting error and a potential legal breach in jurisdictions where distributable reserves are defined as realised profits.
What happens when fair value falls after a prior upward revaluation
If the fair value subsequently falls — say, after the initial €80,000 write-up, the fair value declines by €100,000 — the treatment depends on the existing surplus. The first €80,000 of the decrease reverses the revaluation surplus in OCI: debit revaluation surplus (OCI) €80,000. Only the remaining €20,000 — the excess over the surplus — goes to profit or loss as an impairment or revaluation loss: debit revaluation loss (P&L) €20,000. The logic: the surplus represented a previous gain; you reverse the gain first before recognising a new loss.
Conversely, if a subsequent upward revaluation follows a prior downward revaluation that was expensed through P&L, the standard requires the reversal to be recognised in P&L first (up to the amount previously expensed) before any remainder goes to OCI as a surplus.
Does the revaluation surplus ever pass through profit or loss?
On a straightforward upward revaluation: never. On disposal of the asset, any remaining surplus in the revaluation reserve transfers to retained earnings — not through P&L. However, the gain or loss on disposal itself (proceeds minus carrying amount at date of disposal) does go through P&L. If the asset is impaired below its original cost after a series of write-ups and write-downs, the portion of the loss that cannot be offset against the surplus in equity does flow through P&L. But the pure revaluation surplus — the write-up recognised in OCI — does not reverse through P&L on disposal or on subsequent revaluation.